
A UAE Tax Residency Certificate can support a company’s request for treaty benefits, but it doesn’t replace Corporate Tax registration or determine whether tax is payable. The question behind “tax residency certificate uae corporate tax” is how these separate requirements relate and whether your business needs both. Confusing evidence of tax residency with tax compliance can lead to missed obligations or an application that isn’t ready.
If you’re unsure whether your company qualifies, which documents to prepare or what the certificate can achieve, resolve those questions before applying. This 2026 guide explains when a certificate may be relevant, how to assess eligibility and supporting evidence, and how to prepare an application. It also distinguishes treaty-related residency evidence from UAE Corporate Tax obligations, so you can identify what to verify and when tailored Corporate Tax advisory may help you review your compliance position.
A UAE Tax Residency Certificate (TRC), issued by the Federal Tax Authority (FTA), is an official document confirming the applicant’s UAE tax-residency status for the purpose stated in the application. Its evidential value depends on the relevant rules and the authority or institution requesting it. A foreign tax authority may assess treaty relief under its own procedures. For broader background on the UAE system, see Taxation in the United Arab Emirates.
Keep the documents and their purposes distinct. A TRC is evidence of residence, Corporate Tax registration records a business with the FTA, a tax return reports taxable activity, and a tax assessment communicates the authority’s determination. A TRC alone does not establish an exemption from UAE Corporate Tax.
No. Both processes involve the FTA, but they serve different purposes. A TRC documents tax residence for a stated use, including treaty-related purposes. Corporate Tax registration concerns a taxable person’s registration obligations. Holding a TRC doesn’t, by itself, fulfil registration, return-filing, payment or record-keeping duties. Assess each obligation separately against the business’s circumstances and current FTA requirements.
A business may be asked to provide a TRC to demonstrate UAE residence to a foreign tax authority, including in connection with a Double Taxation Avoidance Agreement (DTAA). The FTA distinguishes treaty-related applications from applications for other purposes. Before applying, confirm who will receive the certificate, what purpose and period it needs to cover, and which treaty conditions may apply. A certificate can support a claim, but it doesn’t guarantee a particular tax outcome.
For UAE Corporate Tax, a TRC may be relevant supporting evidence, but it doesn’t replace an assessment of the entity’s tax position. Confirm separate registration and filing responsibilities using current FTA guidance rather than inferring them from residency documents.
Eligibility for a UAE Tax Residency Certificate depends on the application’s purpose and the FTA’s current requirements. A company’s incorporation, licence or Corporate Tax registration may be relevant evidence, but none should be treated as automatic proof that the entity qualifies for every certificate category. For the wider tax framework, consult the official UAE Corporate Tax guide.
Keep three questions separate: where the entity is resident under the relevant rules, whether it has Corporate Tax registration duties, and what evidence the recipient of a particular application requires. The tax residency certificate uae corporate tax relationship is evidential, not determinative.
| A TRC may evidence | A TRC does not decide |
|---|---|
| UAE tax residence for the stated purpose and period, subject to applicable requirements. | Whether the entity must register, file returns or pay UAE Corporate Tax. |
| Supporting documentation for a foreign authority’s review of a treaty-related claim. | Whether treaty relief applies or the final tax treatment in another jurisdiction. |
Before applying, check the entity type, its establishment and operational facts, and the period covered against the FTA’s current criteria for the selected purpose. Mainland, Free Zone and foreign entities shouldn’t assume eligibility or ineligibility based on status alone. Corporate Tax registration is a separate compliance fact, not a substitute for checking the TRC criteria and evidence relevant to the application.
No. A certificate alone doesn’t create an exemption or determine a Corporate Tax rate. The result depends on applicable UAE law, the business’s facts and, where relevant, the terms and application of a tax treaty. Review those matters separately from the TRC. The certificate is not a tax assessment or a ruling on liability.
If you need to align residency documents with business obligations, a review of Corporate Tax advisory and compliance may help clarify the separate questions to assess.
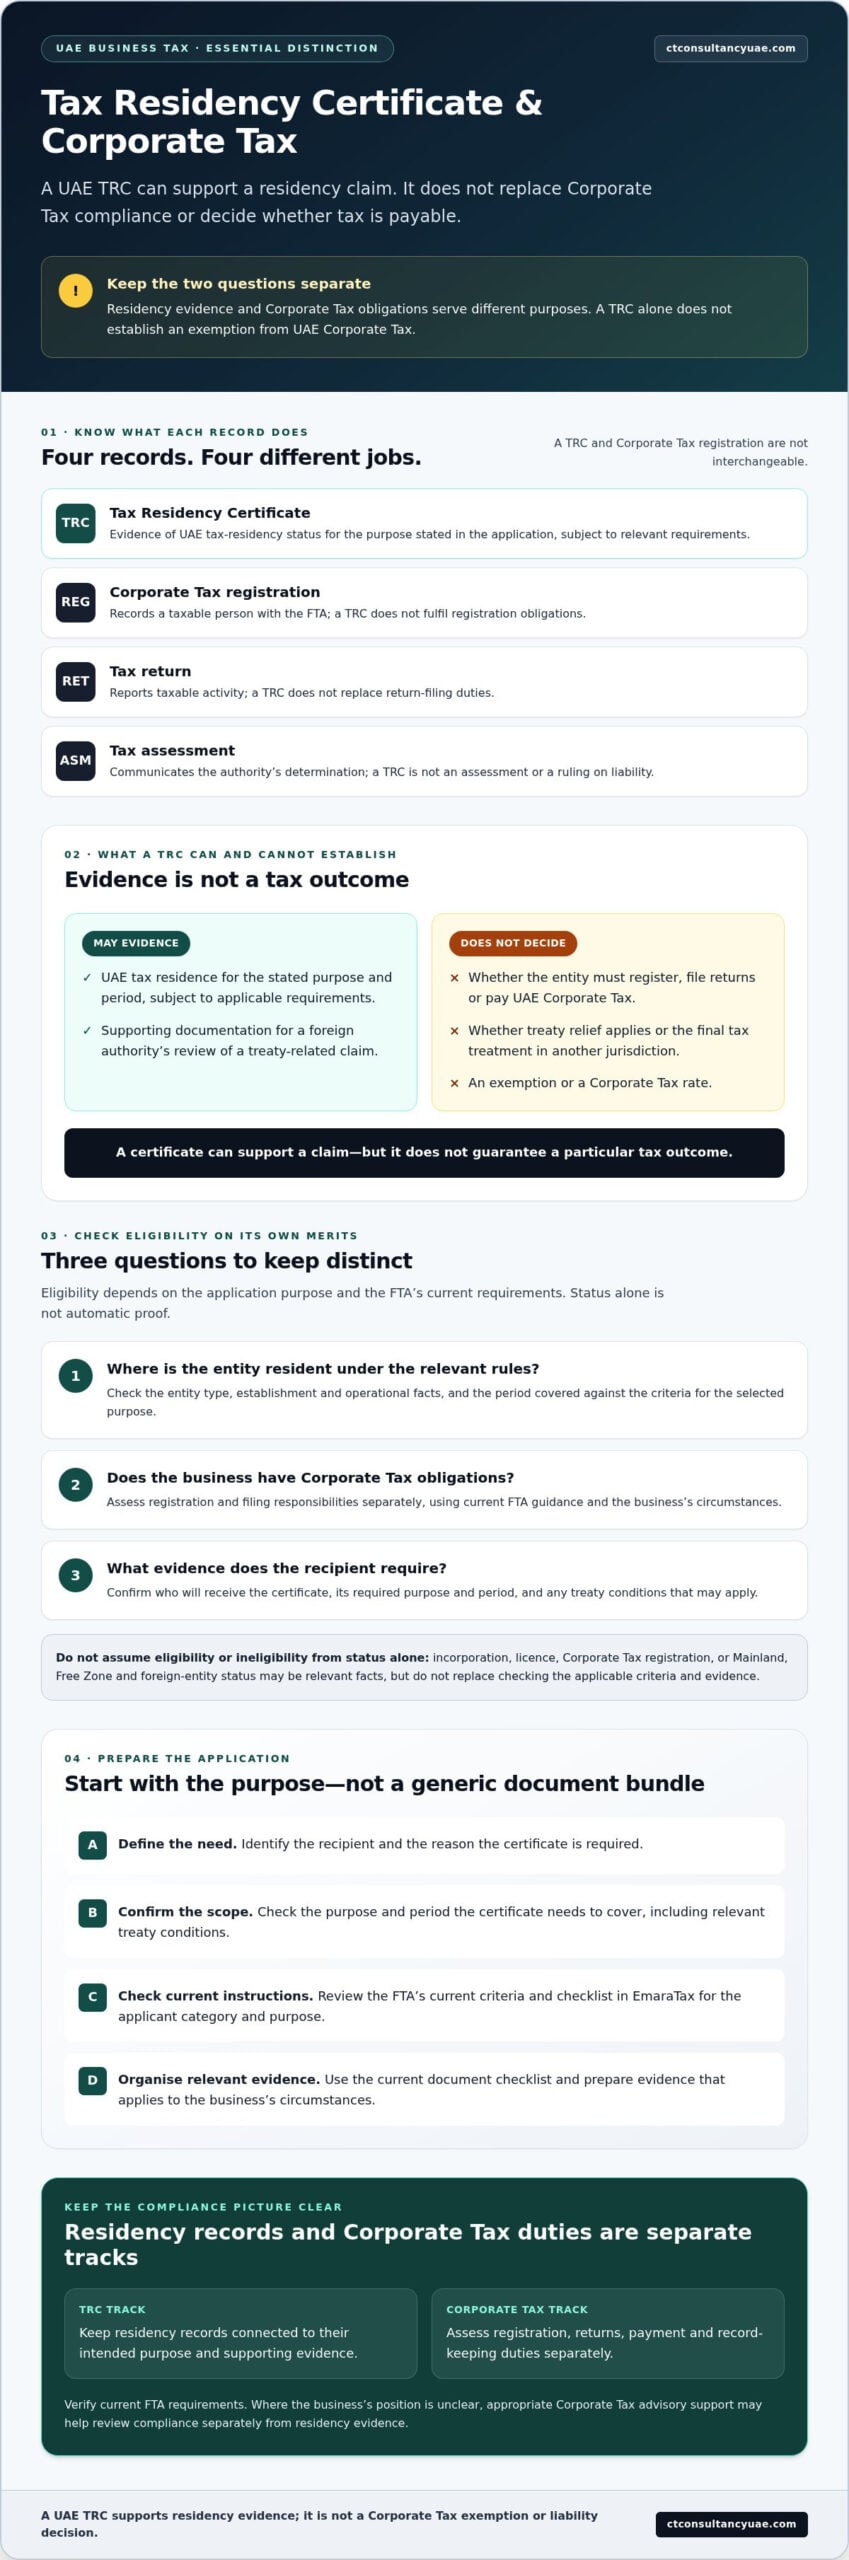
Start with the reason you need the certificate, not a generic document bundle. Requirements can vary by applicant category and purpose, so check the FTA’s current instructions and checklist in EmaraTax before compiling evidence. The UAE Government’s UAE Corporate Tax Law guidance provides wider context, but it isn’t a substitute for the FTA’s live TRC application requirements.
Preparation sequence:
This sequence helps prevent a common mistake: collecting documents before confirming which certificate category and purpose apply. Check the criteria first, then assemble the relevant evidence and retain a complete record of what you submit.
Don’t assume one checklist covers every applicant. Review the current FTA list for the selected certificate purpose and category, then prepare the applicable evidence. Before submitting, compare entity names, identification details and dates across the application and supporting documents. Resolve inconsistencies before filing rather than relying on an explanation later.
Confirm the certificate purpose, applicant category, relevant period and current submission instructions. If the business has unusual circumstances or conflicting records, consider qualified advice before filing. Review the tax residency certificate uae corporate tax connection separately from registration and return obligations. CTC Tax & Accounting provides Corporate Tax advisory to help businesses assess related compliance questions. Explore Corporate Tax advisory services for support with that review.
Receiving a Tax Residency Certificate doesn’t conclude a business’s tax-compliance responsibilities. Continue to assess Corporate Tax registration, return filing, payment and record-keeping obligations independently, based on the business’s facts and current requirements. Under the UAE rules, returns and payments are generally due within nine months after the end of the relevant tax period. Maintain a reliable calendar and confirm the deadline that applies to your entity.
Retain the certificate alongside the application, supporting evidence and correspondence. Record its purpose and period, and make sure the documents can be retrieved if a foreign authority or another relevant party requests them. If the entity, its arrangements or the facts supporting residence change, reassess whether the certificate remains suitable for its intended use. Treat the tax residency certificate uae corporate tax relationship as part of an overall compliance assessment, not a standalone determination.
Consider advice if cross-border arrangements, treaty questions, changes to the entity or conflicting residence facts complicate the analysis. These circumstances may affect how documentation is used, while separate Corporate Tax duties still need to be assessed. A tailored review can help clarify what to resolve before the business relies on its certificate or makes a related tax decision.
Ask prospective advisers about their relevant UAE tax experience, the scope of their work, how they review and organise information, and who is responsible for each step. Confirm whether the engagement covers Corporate Tax compliance only or also considers how residency evidence relates to the business’s circumstances. Don’t assume a tax adviser will submit a TRC application unless that service is expressly confirmed.
CTC Tax & Accounting provides Corporate Tax advisory and tax-compliance support. Review the firm’s UAE tax services as a next step in assessing your obligations, while confirming separately who will handle any TRC application.
A Tax Residency Certificate is most useful when its purpose, supporting evidence and relevant period are clear. It can help document UAE tax residence, but it doesn’t replace a separate assessment of Corporate Tax registration, filing and payment responsibilities. If your business is weighing the tax residency certificate uae corporate tax relationship, review the certificate’s intended use alongside the entity’s own compliance position.
CTC Tax & Accounting provides Corporate Tax advisory and tax compliance services, with support for businesses navigating UAE regulatory requirements. The aim is to help you understand the obligations connected to your circumstances, rather than assume a certificate determines your tax outcome.
Discuss your UAE Corporate Tax requirements with our team to clarify which compliance questions need attention and decide on your next step.
No. A UAE Tax Residency Certificate (TRC) is separate from Corporate Tax registration and isn’t a prerequisite for registering. A TRC may evidence tax residence for a stated purpose, while registration addresses a business’s obligations under UAE Corporate Tax rules. Assess registration and filing duties independently, even if the business holds a certificate or believes its tax liability may be zero.
No. A TRC alone doesn’t exempt a company from UAE Corporate Tax or determine its applicable tax rate. Residency documentation may support a particular purpose, while tax treatment depends on applicable UAE law, the company’s facts and any relevant treaty provisions. Assess those matters separately before relying on the certificate or making a tax decision.
A company may apply if it meets the FTA’s current requirements for the certificate’s purpose and applicant category. Common criteria include legal incorporation and registration in the UAE, and an operational period of at least one year. Mainland and Free Zone entities should verify their specific position. Offshore entities are generally not eligible under the guidance summarised here. Confirm current FTA criteria before applying.
First identify the certificate’s purpose and confirm the company’s applicant category and eligibility. Then check the FTA’s current instructions and document checklist, and submit through the EmaraTax portal if that remains the prescribed route. Review the application and evidence for consistent entity details and dates, then retain the submission and supporting records. Verify the live process before filing, as requirements can vary by purpose.
There isn’t one document set that applies to every company. Depending on the application category and purpose, the FTA checklist may call for items such as a valid trade licence, incorporation certificate, Memorandum of Association, audited financial statements or tenancy evidence. Check the current checklist in EmaraTax before gathering records, and ensure the company’s name, details and relevant dates match across submitted documents.