
What if the salary is only the starting point for the real cost of an accountant? In the UAE, the hidden costs of in-house accounting can include recruitment, visa processing, health insurance, end-of-service gratuity, software, office space and paid leave. These expenses sit in different budget lines, so the full commitment is easy to underestimate.
An in-house employee can offer direct availability and day-to-day knowledge of the business. But relying on one person can leave records, deadlines and specialist work vulnerable to absence or turnover. It can also mean compliance tasks take priority over timely reporting and analysis.
This guide provides a practical framework for assessing direct and indirect costs, then comparing in-house, external and hybrid support against your business’s needs. You’ll learn how to weigh employment overhead against capacity, continuity and compliance responsibilities, including UAE tax and financial reporting. The goal is to choose an accounting structure that fits your operational complexity and plans for growth.
An in-house accountant can give owners direct oversight, quick access to financial information and a familiar point of contact. Those advantages matter, but payroll alone doesn’t show the full operating commitment. The hidden costs of in-house accounting include the recurring and occasional resources needed to keep the function effective and dependable, beyond the employee’s stated compensation.
“The full cost of in-house accounting is the compensation, systems, oversight and support needed to maintain reliable financial operations.” That means considering both direct employment expenses and the time and resources the business contributes behind the scenes.
Group costs into five categories: people, systems, management, continuity and specialist support. Payroll and software subscriptions are relatively predictable. Recruitment, onboarding, temporary cover and audit preparation may occur less often, but still belong in a realistic assessment. Which costs matter most depends on transaction volume, reporting needs and the complexity of the business’s accounting.
A salary-only comparison can leave out the time managers spend supervising work, recruiting and training a new hire, or arranging cover when the employee is unavailable. It can also obscure capacity constraints. For example, routine transaction processing may take priority over analysis and timely reporting when one person is responsible for both.
In the UAE, VAT and Corporate Tax responsibilities add recurring recordkeeping and filing work. Include these tasks when estimating workload, and consider whether your team has the expertise and capacity to complete them alongside regular reporting. Management accounting illustrates how financial information supports internal decisions and performance assessment. One employee may suit some businesses; others benefit from combining internal ownership with specialist support.
Build your assessment around the work required to maintain accurate books and useful financial information, rather than relying on a single payroll figure. In the UAE, VAT and Corporate Tax responsibilities can add documentation, reconciliations and filing preparation to routine transaction processing. The workload depends on the company’s activities, transaction patterns and reporting requirements.
“A complete assessment considers staffing, systems, management time, specialist work and the operational impact of interruptions.” Use these categories as a checklist, then identify which ones apply to your business and how often the associated work occurs.
Separate recruitment and onboarding from ongoing training, supervision, leave cover and retention. Each requires different resources. Then review the systems that support accounting: software, expense workflows, integrations and access controls all require setup and ongoing attention. Include senior managers’ time spent reviewing records, resolving process gaps and tracing missing information. These demands may not appear as a separate expense, but they still use business capacity.
VAT and Corporate Tax work can involve regular coordination between source records, reconciliations and filing preparation. Where IFRS-aligned reporting is relevant, account for the processes and review needed to produce consistent financial information. Reporting requirements are not identical for every business. Backlogs can delay month-end visibility, while absence or undocumented procedures can make handovers difficult and interrupt routine work.
To make the assessment practical, review a representative reporting period and record who completes each task, which system or evidence it depends on, and where review or specialist input is needed. This helps identify whether the pressure comes from transaction volume, fragmented workflows or limited continuity. Businesses assessing their accounting support requirements can use the same categories to pinpoint where additional capacity would help.
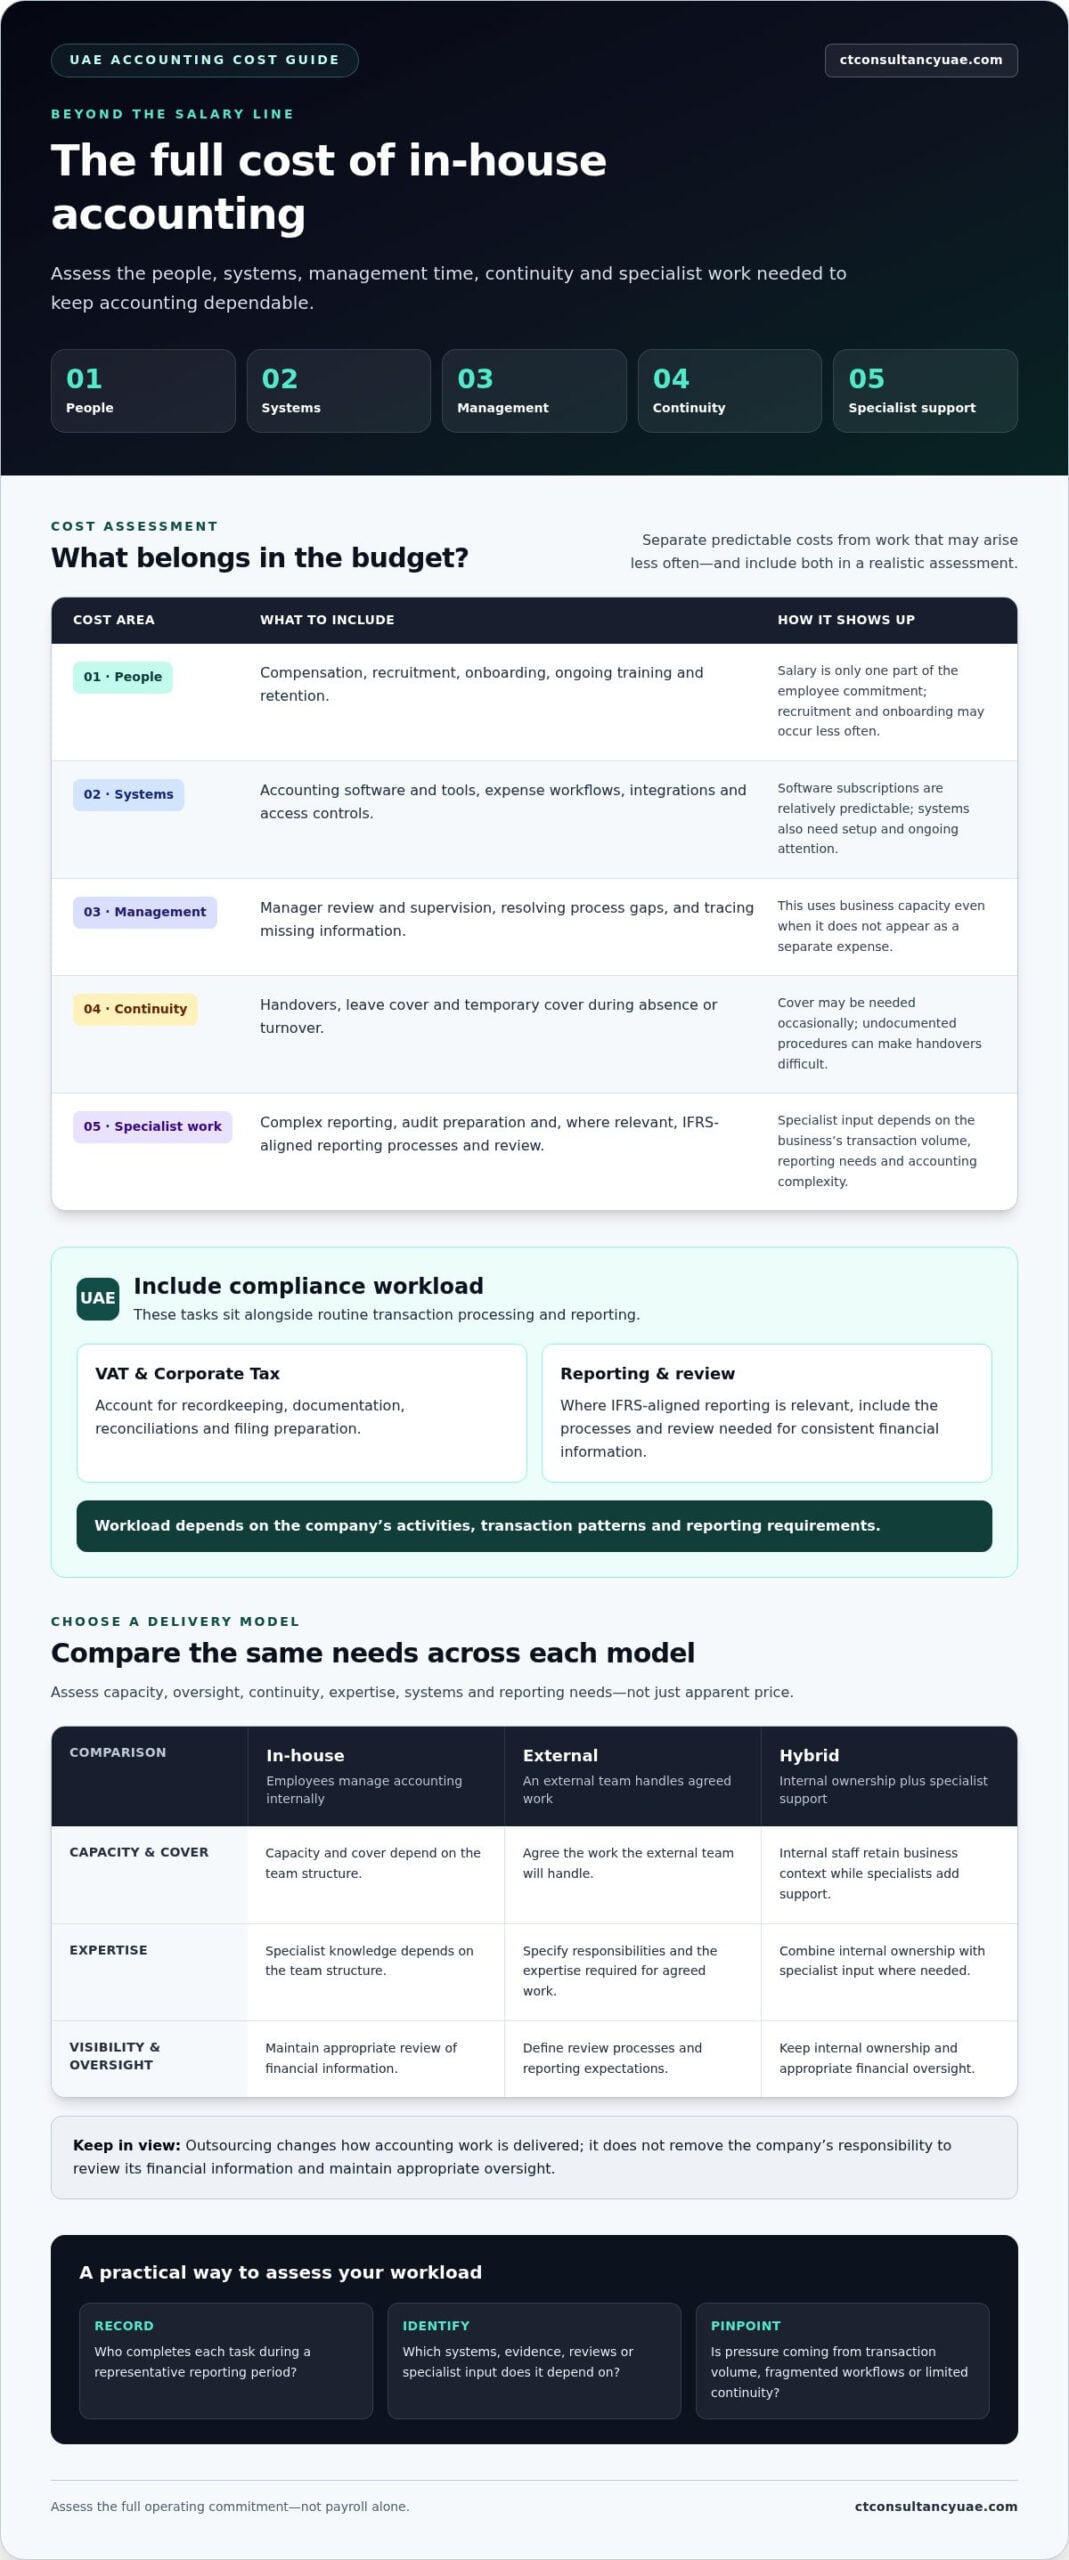
Compare each model against the same workload and reporting requirements, not just its apparent price. Assess capacity, oversight, continuity, expertise, systems and reporting needs. Then specify who owns each task and how the business will retain visibility. Outsourcing changes how accounting work is delivered; it does not remove the company’s responsibility to review its financial information and maintain appropriate oversight.
| Model | Typical arrangement | Key consideration |
|---|---|---|
| In-house | Employees manage accounting internally. | Capacity, specialist knowledge and cover depend on the team structure. |
| External | An external team handles agreed accounting work. | Define responsibilities, review processes and reporting expectations. |
| Hybrid | Internal staff retain business context while external specialists add capacity. | Clarify handovers, access and accountability between teams. |
An internal role may fit when transaction volume is sustained, regular coordination with other departments is essential, and the responsibilities add up to a clearly defined position. Before hiring, list recurring tasks and the expertise they require, including the reporting and review expected. Assess the hidden costs of in-house accounting alongside these operational benefits. The best structure depends on the company’s workload and priorities.
External support can handle recurring recordkeeping, reporting or backlog work. A hybrid arrangement lets internal staff retain day-to-day business context while specialists add capacity or expertise. Businesses can align outsourced bookkeeping services with their workflow and add broader financial management as reporting needs evolve. A clear division of responsibilities helps maintain oversight without assigning every task to one employee.
Use the comparison to locate gaps in your current structure, then match support to those specific needs. CTC’s Accounting Services cover monthly bookkeeping, backlog handling, accounts payable and receivable, monthly financial reporting and audit preparation.
Once you know where time and capacity are being used, turn the assessment into an operating plan. The hidden costs of in-house accounting are easier to manage when recurring tasks have clear owners, review points and reporting expectations. Documented processes also make work less dependent on informal handovers or one person’s memory.
Start with a representative month. Document the work to be completed, who provides the information and who reviews the result. Use this sequence to turn observations into decisions:
This map can show whether the main gap is bookkeeping capacity, compliance support, management reporting or financial planning. If forecasting and financial oversight are priorities, CFO advisory services can complement routine accounting with budgeting, cash-flow forecasting, financial dashboards, KPI analysis and reporting.
CTC’s a-la-carte Accounting Services can be matched to identified needs, including monthly bookkeeping, backlog handling, accounts payable and receivable, monthly financial reporting and audit preparation. Set out the deliverables, information handover and review cadence so management retains visibility, whether work is handled internally, externally or through a hybrid arrangement. Adjust the scope as transaction patterns and reporting requirements change.
For a tailored discussion about your accounting workload and oversight needs, CTC offers a 20-minute free* initial consultation.
Your accounting model doesn’t have to be permanent. As transaction patterns, reporting expectations and management priorities change, review whether the balance of internal ownership and external support still works. A clear view of responsibilities can help you adjust capacity before routine processing limits the financial insight needed for decisions.
CTC Tax & Accounting, founded in 2015, brings 75 years of combined international finance and accountancy experience to businesses reviewing their options. Its a-la-carte Accounting Services and virtual or on-site CFO Services can support different operational and financial oversight needs. A useful starting point is your current workload, reporting priorities and plans for growth, rather than an assumption that accounting must be delivered in one particular way.
Take the next step with a focused review of your requirements. Book a 20-minute free* consultation to discuss an accounting support structure suited to your business and how to address the hidden costs of in-house accounting.
The hidden costs of in-house accounting are the resources needed to keep the function running beyond the employee’s stated compensation. They can include hiring and onboarding, software administration, management review, cover during absence and occasional specialist assistance. To make these costs visible, review a full operating cycle and record both direct expenses and staff time diverted from other responsibilities.
Not necessarily. The answer depends on the tasks included, the internal capacity required and the expertise the business needs. Compare equivalent deliverables, such as transaction processing, reconciliations and management reports, rather than comparing salary with an external service fee alone. An in-house role may suit sustained internal coordination, while external support may fit a defined or changing workload.
Accounting software can support transaction recording, document workflows and routine report preparation, but it does not provide business judgment or management accountability on its own. A system may capture a transaction, for example, while a person still needs to assess its context, resolve an exception and review its effect on reporting. Budget for both the technology and the oversight needed to use its outputs responsibly.
Consider external support when bookkeeping falls behind, reporting deadlines become difficult to meet or internal staff lack capacity for a new workload. It can also support continuity during rapid growth or a change in finance personnel. Define which records and deliverables need support, who in the business reviews them and how information will be shared securely.
Use the same period and task list for both options. Record employment-related expenses, systems and internal review time, then compare them with the external work included and any tasks that would remain in-house. Include less frequent work by reviewing a full year, not just a typical month. Finally, assess whether each model provides the continuity, expertise and reporting your business requires.