
Could a polished AML policy still leave your UAE business exposed to compliance failures? The right expert aml guidance to avoid fines starts with a more fundamental question: which obligations apply to your activities and supervisory context? A generic checklist can’t answer that or show whether controls work in daily operations.
It’s understandable to be concerned about missed reporting duties, incomplete customer records, or procedures that exist on paper but aren’t followed consistently. The UAE’s Federal Decree-Law No. (10) of 2025 and its implementing Cabinet Resolution No. (134) of 2025 make it important to assess your current framework against the requirements that apply to your business.
This guide explains how to identify relevant AML obligations, examine risk assessment and customer due diligence practices, and spot gaps in reporting, recordkeeping, and oversight. You’ll also learn how tailored AML support, supported by internal audit and ongoing compliance oversight, can help organize practical remediation and strengthen readiness without promising a penalty-free outcome.
AML compliance means identifying and managing the risk that a business could be used to launder money or finance terrorism or proliferation, while meeting the obligations that apply to its activities. It isn’t a promise that fines can never arise. Instead, it means putting proportionate controls in place and keeping evidence that helps show how the business meets its duties and responds to risk. For foundational context, see this overview of Anti-money laundering (AML) laws and regulations.
In the UAE, the federal framework includes Federal Decree-Law No. (10) of 2025 and Cabinet Resolution No. (134) of 2025. Obligations depend on what an entity does, where it is regulated, and which supervisory authority oversees it. Another business’s procedures may not address the same activities, risks, or reporting duties as yours.
Requirements can apply to financial institutions and designated non-financial businesses and professions (DNFBPs). Relevant activities may include real estate brokerage, accounting, specified legal services, and dealing in precious metals or stones; virtual asset service providers are also within the expanded framework. The Central Bank supervises financial institutions, while DNFBP oversight and free-zone regulation vary by activity and entity. Identify your business category, applicable supervisory context, and reporting duties before deciding which controls are needed.
A risk assessment without supporting reasoning, procedures applied inconsistently, or an undocumented escalation can make it difficult to demonstrate that controls are effective. For example, a business may identify a higher-risk customer but lack a record showing why enhanced checks were applied, who reviewed the concern, or how it was resolved. Reviewing the decision trail can reveal whether the issue is missing documentation, unclear responsibility, or a control that wasn’t followed.
Supervisory consequences for compliance failures are distinct from criminal outcomes, which depend on the conduct and applicable law. Expert aml guidance to avoid fines means tailoring AML controls to a business’s actual exposure and documenting how they operate; it cannot guarantee a penalty-free outcome. An individualized review can help clarify obligations and identify evidence or escalation gaps before they become harder to address.
A usable AML framework connects the risks a business has identified to controls employees can apply and management can oversee. Controls should be proportionate to assessed exposure, with a clear record of how decisions were made. Review the framework periodically, especially when activities or risk conditions change.
Record the assessment method, material risks identified, rationale for control decisions, responsible owners, and review dates. Keep supporting policies, approvals, monitoring records, and follow-up actions organized so the assessment can be linked to how controls operate. For each identified risk, note which control addresses it and what evidence shows that the control was applied. Revisit the assessment when business activities, customer profiles, products, channels, or relevant risk conditions change.
Leadership should assign accountable roles and clear reporting lines, including who can raise concerns and how unresolved issues reach decision-makers. Responsibilities must fit the entity’s applicable AML regime; formal role requirements can vary by activity and supervisory context. Clear ownership helps prevent alerts or control failures from being left without review. Written procedures should make it clear who records a decision and who follows up on any action.
Documented procedures matter only when they are applied consistently. Internal audit and ongoing compliance oversight can help assess whether approvals, reviews, and escalation records support the framework in practice. For businesses seeking expert aml guidance to avoid fines, a tailored review can help prioritize control gaps and organize remediation. CTC Tax & Accounting provides AML compliance support, and its business advisory support can also form part of a broader financial oversight approach.
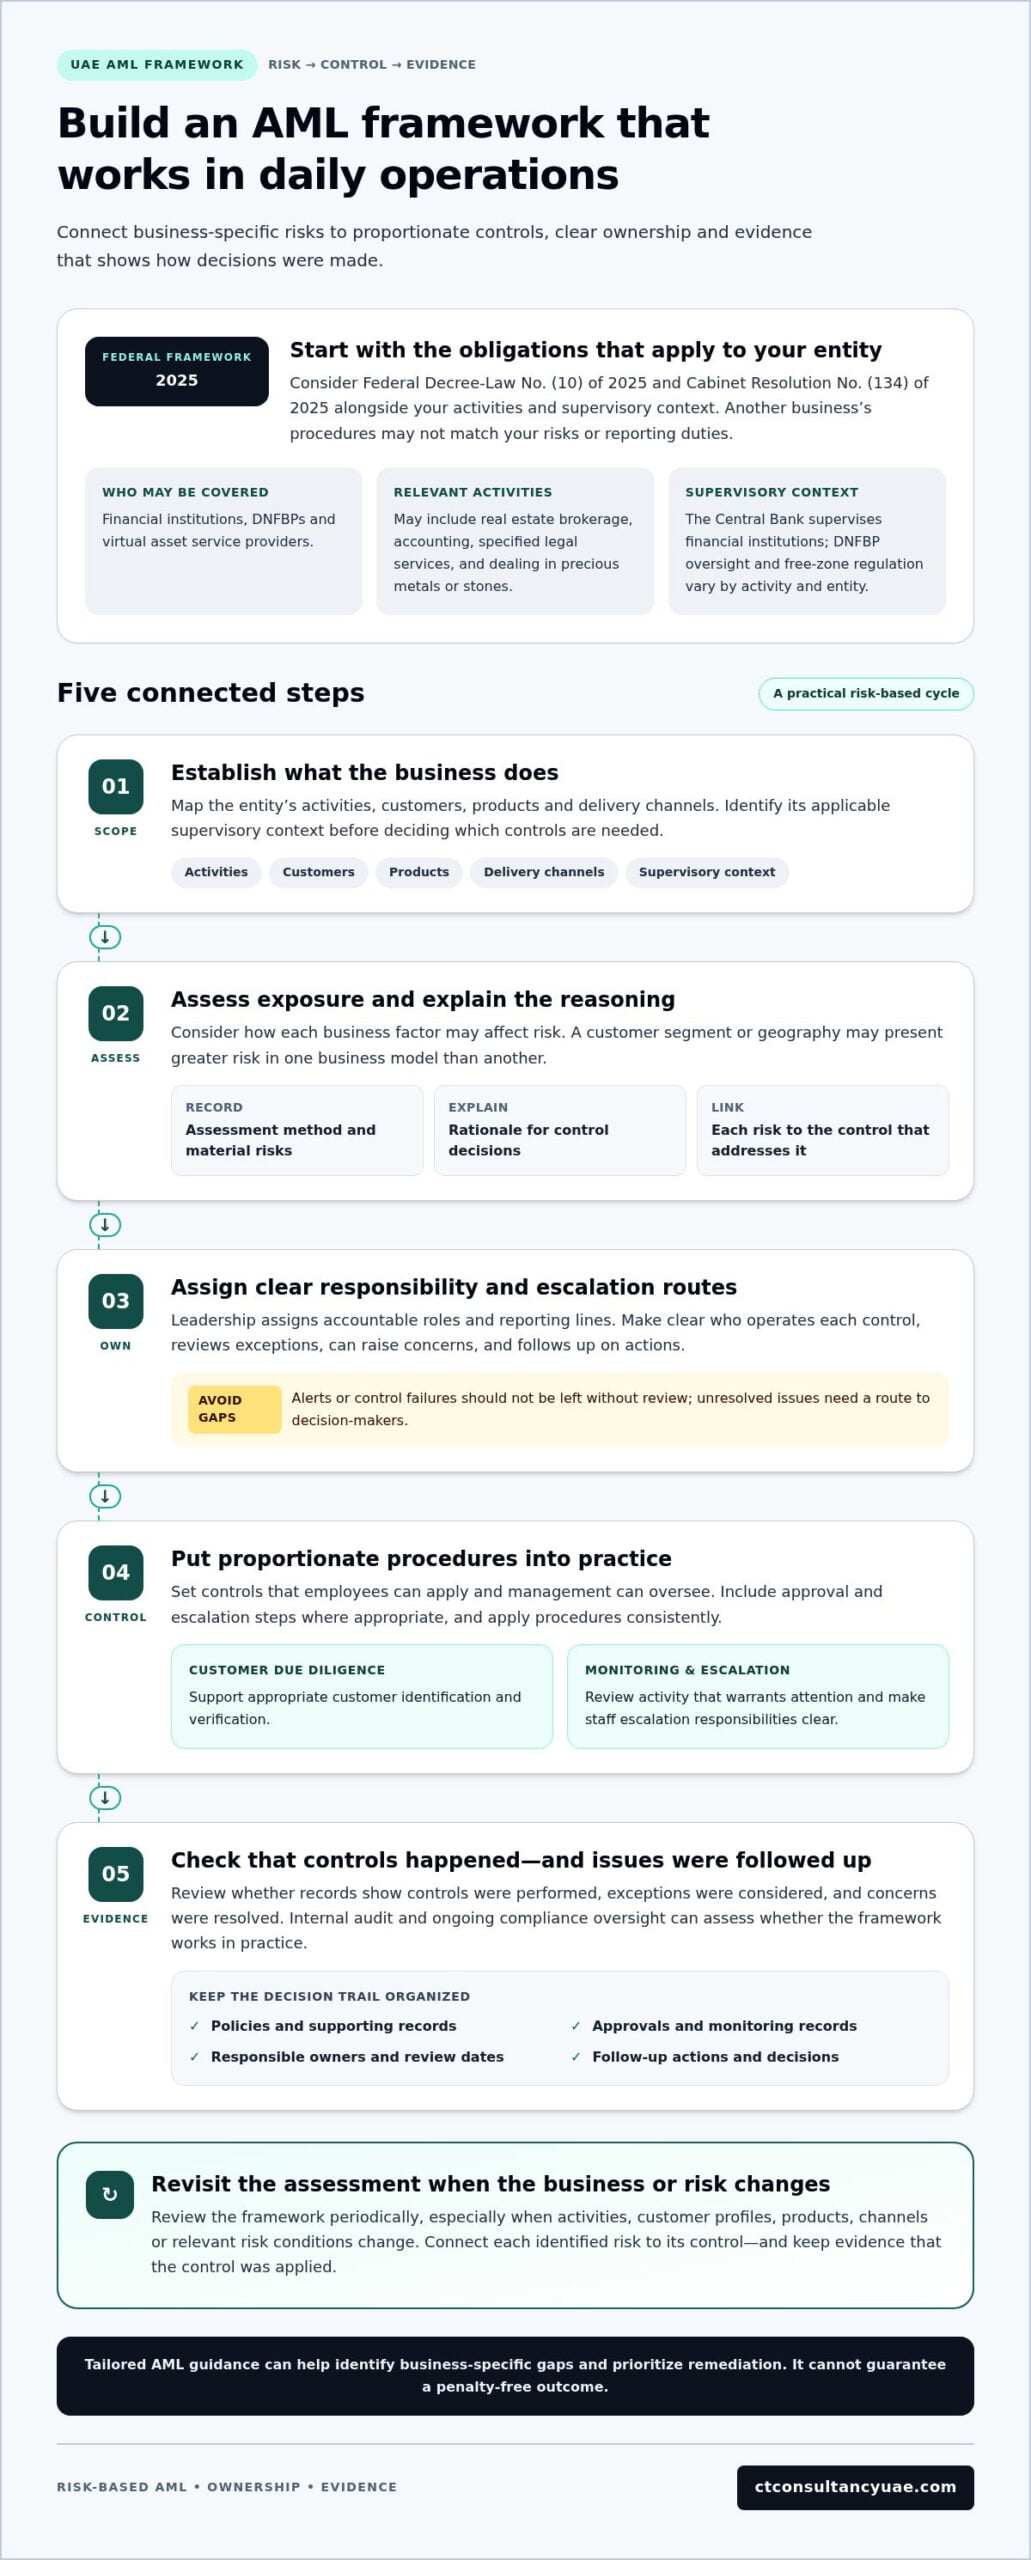
Make routine checks consistent with the entity’s applicable requirements and documented risk assessment. Customer due diligence should support appropriate identification and verification; ongoing monitoring should help detect activity that warrants review. Staff need to know how to escalate concerns, while training and record maintenance should make responsibilities and decisions traceable. A useful test is to select a documented control and follow its evidence from the initial check through review, decision, and any follow-up.
A practical evidence checklist includes:
Compare written procedures with actual files and workflows. If policy requires a review before onboarding a higher-risk customer, confirm that records show the review, decision-maker, rationale, and any follow-up. Check that alerts and exceptions have a documented outcome, training records reflect completed sessions, and corrective actions can be traced to closure or an active plan. Where evidence is missing, establish whether the control was not performed or whether the recordkeeping process failed to capture it.
Prioritize findings according to potential risk, assign an accountable owner, set a practical target date, and record progress and evidence of completion. Separate urgent control weaknesses from process improvements that can be scheduled, and keep a record of management decisions about each finding. Expert aml guidance to avoid fines can help identify and address avoidable control weaknesses, but no adviser or checklist can guarantee that a business will never face a regulatory action.
AML duties should also be kept distinct from other compliance regimes. For example, Economic Substance Regulations have their own scope and requirements, rather than serving as a substitute for AML controls. Reliable financial records and audit trails can support broader oversight; review your accounting records and processes as part of that work.
CTC Tax & Accounting provides AML compliance support, and its accounting services can help businesses maintain organized financial records. For a tailored review of AML procedures, evidence, and remediation priorities, explore CTC’s accounting services alongside its compliance support.
An expert review can be valuable when business activities change, responsibility for AML controls is unclear, records are incomplete, or earlier findings remain unresolved. These issues can leave decision-makers unsure whether procedures still fit the business’s risk profile or whether available evidence shows how controls work in practice.
A focused advisory process should move from understanding the business and its applicable obligations to assessing existing controls, prioritizing gaps, and supporting remediation. The outcome should be specific to the business: documented recommendations linked to identified risks, with clear priorities and practical next steps, rather than a generic template or blanket assurance.
A useful review considers the business’s activities, risk assessment, control design, responsibilities, and supporting records. It should distinguish more urgent weaknesses from improvements that can be planned, explain the rationale for each recommendation, and give management a basis for tracking corrective action. Expert guidance supports compliance readiness, but it cannot guarantee that a regulator will not impose a measure or that a particular outcome will follow.
AML control reviews can complement internal audit and ongoing accounting oversight by examining whether documented procedures align with operational and financial records. This can help management see control issues in context, follow remediation, and maintain a clearer audit trail. CTC Tax & Accounting provides AML compliance, internal audit, and accounting services to support this wider view of financial oversight. Learn more about the firm’s background and compliance support on the CTC Tax & Accounting profile.
For UAE businesses seeking expert aml guidance to avoid fines, tailored AML compliance support can help clarify obligations, identify business-specific gaps, and organize a proportionate response. Discuss your requirements with CTC Tax & Accounting to explore tailored AML compliance support.
Effective AML compliance starts with understanding which obligations apply to your business, then translating that understanding into risk-based controls with clear ownership and reliable evidence. Regular reviews help identify gaps early, while documented escalation and remediation make it easier to demonstrate how concerns are handled. Expert aml guidance to avoid fines can support stronger readiness, but no adviser can guarantee a particular regulatory outcome.
CTC Tax & Accounting provides AML compliance and internal audit services to help businesses connect control design with practical oversight, identify business-specific weaknesses, and organize remediation. Its accounting and advisory services can also support wider financial oversight.
Take the next step toward a more structured compliance approach. Discuss tailored AML compliance support with CTC Tax & Accounting and build a clearer path to stronger controls and sustained readiness.
No. Expert AML guidance can help a UAE business understand its applicable obligations, assess controls, and address weaknesses, but it can’t guarantee that fines will be avoided. Regulatory outcomes depend on the facts, the entity’s applicable regime, and the relevant authority’s assessment. The value of expert aml guidance to avoid fines is stronger compliance readiness and fewer preventable gaps, not a promise of a penalty-free result.
AML duties don’t apply identically to every UAE business. They may apply to financial institutions and designated non-financial businesses and professions, with scope depending on activities and supervisory context. Relevant activities can include specified real estate, accounting, precious-metals, and virtual-asset services. Businesses should identify the rules and reporting duties relevant to their own category rather than copy another firm’s controls.
An AML review typically examines whether obligations have been identified correctly and whether risk assessments, customer due diligence, monitoring, escalation, training, and recordkeeping controls are appropriate to the business. It can also compare written procedures with actual practice, test how exceptions were handled, and identify unresolved findings. The review’s scope should reflect the entity’s activities, risks, and applicable supervisory requirements.
Review AML controls regularly and whenever a material change could affect the business’s risk profile, such as a new activity, product, customer type, or delivery channel. Reassess controls after an internal review identifies weaknesses or when relevant requirements change. Any prescribed review frequency depends on the entity’s applicable regime, so verify specific requirements and document when reviews occur and what actions follow.
Maintain records that show both the design and operation of controls, including AML policies, risk assessments, customer due diligence, monitoring and review logs, escalation decisions, training records, approvals, and issue remediation. Keep supporting evidence organized so decisions can be traced to the relevant review and accountable owner. Applicable rules determine recordkeeping requirements and retention periods, so verify these for your business and supervisory context.